
Invoice Discounting
Take control of your cashflow the confidential way
What is Invoice Discounting?
Invoice discounting is also known as Confidential Invoice Discounting or CID. Like all facilities associated with invoice finance, invoice discounting allows you to release cash from outstanding invoices. However, this facility remains confidential, and your clients do not have to know that you have a facility. To ensure it is kept confidential, credit control is conducted by your business and a lender’s notice of assignment does not appear on your invoices.

How does Invoice Discounting work?
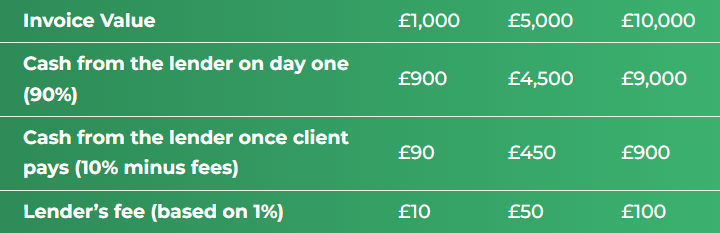
Invoice discounting allows you to release up to 90% of the gross invoice value, the same day you raise the invoice. Having an invoice discounting facility with the right lender can work for businesses that are cash hungry but do not want clients to know that they have such financial support from a lender. The process is simple:
Example
Three Easy Steps
Step One
You invoice your clients as normal and also send a copy of the invoice to the lender.
Step Two
You receive up to 90% of the gross invoice value straight away, without any issues.
Step Three
The remaining 10% is made payable to your business minus the lender’s fees.
How much does Invoice Discounting cost?
Confidential invoice discounting is generally more competitive than other forms of invoice finance facilities. The service charge is generally slightly less than invoice factoring because you are not having to pay for the lender to assist with credit control and chase clients for payment.
Calculate Your Potential Payments
Your Results
You Could Access
i
The same day you raise the invoice
Estimated Cost
i
What it could cost to borrow against the invoice
Estimated % of the invoice
i
As a flat percentage, how much an invoice finance facility will cost. This is also the fee to have in mind if you need to make invoice finance pay for itself
Take Control of Your Cashflow
- Offer extended terms to clients
- Release up to 90% of the invoice value
- Fast & flexible funding tailored to your needs
- Get paid faster
Frequently Asked Questions
What are the advantages of Invoice Discounting?
Improves your cash flow – invoice discounting allows you to grow your business by simply getting paid quicker. This allows your business to have a steady cashflow, not have to wait for clients to pay on time and trade efficiently.
Confidential – this means that your clients do not have to be aware that you have the financial backing of a lender. Some business owners prefer this.
Potential discount from suppliers – invoice discounting can sometimes pay for itself. This is because a business can now afford to pay suppliers sooner and potentially negotiate a discount from them.
Safe way to borrow – as your business grows, so does your funding. Unlike a traditional loan, you can only borrow against cash that you are already owed by clients. Therefore, there is no risk of falling behind on payments.
Release up to 90% of the invoice value – this is not only for future invoices, but you can also drawdown against your existing sales ledger, as long as the invoices are not older than 90 days.
Speed – you can release cash from an outstanding invoice on the same day. Therefore, you no longer have to wait for clients to pay and you can trade more efficiently.
What are the disadvantages of Invoice Discounting?
More admin – you must conduct credit control in house and lenders quite often need management accounts to be produced on a monthly / quarterly basis. This is because there is less transparency associated with this form of invoice finance facility.
Debenture search – if your clients wanted to search your business, they could still see if a lender has registered a debenture charge on companies house and know of the lenders involvement.
Terminology – not all lenders use the same terminology and call it invoice discounting. It is quite often referred to as a CID facility which is just an abbreviation of ‘Confidential Invoice Discounting’.
Is Invoice Discounting a good idea for my business?
Confidential invoice discounting can be great for a business that needs a steady cashflow. It allows businesses to have that constant working capital required to trade efficiently. Invoice discounting is generally for bigger businesses who have systems in place to conduct credit control and can produce management accounts on a lenders request.
What is the difference between Invoice Discounting and Invoice Factoring?
Invoice discounting is confidential, and you keep credit control in house. Invoice factoring is fully disclosed, and the lender assists with credit control and often speaks to clients.
How confidential is Invoice Discounting?
Invoice discounting is the most confidential version of invoice finance. Debtors are not contacted by the lender and the lender’s notice of assignment does not have to appear at the bottom of your invoices. Please note, that if a client wanted to do a company search on your business on Companies House, they will be able to see all lenders that take a charge on the debenture. This is the same for various forms of business borrowing.
Is Invoice Discounting available to new start businesses?
Invoice discounting is not normally available to new start businesses. However, if you have a proven track record and suitable systems in place, we can certainly find you an invoice finance lender that can accommodate an invoice discounting facility.
How does Invoice Discounting work?
You send your sales ledger to the invoice finance lender
They release up to 90% of the gross sales ledger balance (inc the VAT)
Your business then conducts the credit control and chases payments
The remaining 10% is payable back to your business once your clients pay (minus the lenders charges)
Accounts and ledgers are reconciled frequently
How do I apply for Invoice Discounting?
Speak to Contact Business Finance today and we will put your business in contact with the most suitable lender.
All we need to do is have a 15-minute conversation to find out more about your business and your funding requirements.
What information do I need to provide for Invoice Discounting?
It is important to have suitable accounting systems in place for an invoice discounting facility. You need to be able to operate your own ledgers and provide management information such as, a balance sheet, profit & loss account and trial balance. Such information can be provided manually to the lenders. However, there are even lenders that can plug into your accounts package such as, Sage, Xero and QuickBooks to make this reconciliation process automatic and easier if required.
Lenders are more interested in what they are funding against – the invoices. Therefore, if you have a clear paper trail in the run up to raising an invoice, lenders can get comfortable.
Can Invoice Discounting be more cost effective?
Invoice discounting can be more cost effective if you have the people and processes already in place to conduct tasks such as credit control. The service charge is often more competitive because the lender is not having to chase payments with an invoice discounting facility.
What if I need assistance with credit control?
If your business suddenly needs assistance with credit control, the majority of lenders can assist. If credit control is constantly needed, you might be best suited to an invoice factoring facility instead, where credit control is included.
How long are Invoice Discounting contracts?
Contract periods vary depending on what lender you go with. There are several lenders in the marketplace that offer trial periods. Many lenders offer 12-month contracts and if required can offer longer contracts to give your business security that you have a funding partner long term.
Can I pick and choose invoices with Invoice Discounting?
Yes, there are certain facilities available that allows a business to pick and choose which clients to include in a facility. The rates are generally not as competitive for such a facility as there is less turnover going through the facility. However, it is an option worth considering if an invoice discounting facility is only required short term.
Can I offer clients credit terms with Invoice Discounting?
Any form of invoice finance allows you to offer extended credit terms to clients. This is often a great weapon to have in your armoury if you are a competing to win a contract. With invoice finance, lenders will quite often lend against invoices for 120 days and sometimes longer depending on what industry you operate in. Please note, you should not just offer extended credit terms to anyone. Part of any invoice finance facility can also include the lender doing in depth credit searches on your clients, so you can see what terms / limits are suitable to offer.
What type of businesses use Invoice Discounting?
Any business that raises an invoice to another business on credit terms can apply for an invoice finance facility. Generally, we find that invoice discounting facilities are for established businesses that require that extra working capital to assist with cash flow. Releasing cash from your invoices is a great way to inject money into the business which often means you can afford to take on more work. With invoice discounting you no longer have to wait to get paid by your debtors before moving onto the next job.