
Invoice Factoring
Take control of your cashflow with funding and credit control
What is Invoice Factoring?
Invoice factoring is a facility associated with the invoice finance industry. Like all invoice finance facilities, factoring allows you to release cash from outstanding invoices. One key feature of an invoice factoring facility is that it includes credit control. This can save you time and money as you no longer need to chase your clients for payment.
Over 44000
Companies in the UK using Invoice Finance
Over 23.7 billion
Invoices in the UK
Over 14600 coffees
Consumed at Contact Business Finance
How does Invoice Factoring work?
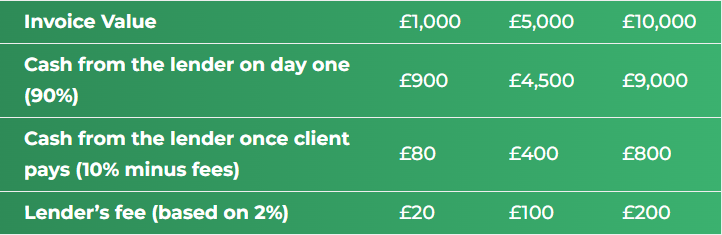
Invoice factoring is a straightforward facility that allows you to release up to 90% of the gross invoice value, the same day you raise the invoice. Having an invoice factoring facility with the right lender can work wonders for businesses that are cash hungry, but do not have the time to chase invoices. The process is simple:
Example
Three Easy Steps
Step One
You invoice your clients as normal and send a copy to your invoice finance lender
Step Two
You will receive up to 90% of the gross invoice value the same day
Step Three
The remaining 10% is made payable to your business, minus the lender’s fee
How much does Invoice Factoring cost?
There are over 100 different invoice factoring lenders in the market who all charge different rates. All of these lenders consist of banks, independent lenders and other finance houses.
Generally, your business will get a better rate the larger the turnover, but this is dependent on many things. For example, your industry, amount of borrowing and any previous business history.
An invoice factoring facility will cost anything from 1-3% of the invoice value.
Calculate Your Potential Payments
Your Results
You Could Access
i
The same day you raise the invoice
Estimated Cost
i
What it could cost to borrow against the invoice
Estimated % of the invoice
i
As a flat percentage, how much an invoice finance facility will cost. This is also the fee to have in mind if you need to make invoice finance pay for itself
Take Control of Your Cashflow
- Offer extended terms to clients
- Release up to 90% of the invoice value
- Fast & flexible funding tailored to your needs
- Get paid faster
Frequently Asked Questions
What are the advantages of Invoice Factoring?
Improves your cash flow – invoice factoring allows you to grow your business by getting paid quicker. This allows you to have the working capital to move on to the next job / order sooner.
Pay suppliers promptly – invoice factoring can sometimes pay for itself, this is because you can often get discounts from suppliers as you can pay them quicker.
Scalable & secure – as your business grows, so does you’re funding. You can only borrow against cash that you are already owed by clients.
Release up to 90% of the invoice value – this is not only for future invoices, but you can also drawdown against your existing sales ledger if the invoices are not older than 90 days.
Speed – you can release cash from an outstanding invoice on the same day. Therefore, you no longer must wait to get paid which means you can move onto the next job sooner.
Save time & money – you no longer have the hassle of chasing payments and can concentrate on more important aspects of your business.
What are the disadvantages of Invoice Factoring?
B2B sales only – invoice factoring companies will only fund invoices that are raised to other businesses.
Terminology – not all lenders use the same terminology, and it can be very confusing if you are new to invoice factoring. However, we can help you understand this financial jargon.
Confidentiality – invoice factoring is fully disclosed, so your clients know that you have a facility. Some business owners prefer to keep their funding solutions confidential. If that is the case, then invoice discounting could be more suitable for you. Please click here to find out more about invoice discounting.
Is Invoice Factoring a good idea for my business?
If you are a cash hungry business and constantly need a steady cashflow, then invoice factoring could be a great solution for you. Waiting 30, 60 or even 90 days is simply too long. Unfortunately, when you start dealing with bigger clients, they often take longer to pay even if you strictly offer specific payments terms. An invoice factoring facility allows you to offer extended payment terms, giving you the opportunity to work with bigger businesses and grow your company. Invoice factoring does not only allow businesses that much needed working capital, but it also saves you time and money as credit control can be outsourced to the lender.
Is Invoice Factoring regulated?
Invoice factoring is currently not regulated by the Financial Conduct Authority. There are however bodies that oversee fair practise such as UK Finance, previously known as ABFA (The Asset Based Funding Association).
What is full Factoring?
Full factoring refers to a facility in which the business includes all of their clients’ sales invoices and receive the maximum amount of funding available from their sales ledger.
What is the process of an Invoice Factoring facility?
- You send a copy of your invoices to the invoice factoring company
- They release up to 90% of the gross invoice value (inc the VAT)
- The invoice factoring company chase debts when they are due and conduct credit control
- The remaining 10% is payable back to your business once your clients pay (minus the lenders charges)
Is Invoice Factoring considered a loan?
Invoice factoring is a form of invoice finance and is often misconceived as a loan. Invoice factoring involves a lender purchasing the sales invoices of a business for a discounted rate. The business can then use this money to contribute towards their growth plans. Invoice factoring is more scalable and secure compared to a business loan. This is because your borrowing increases in line with your sales and you can only borrow against sales invoices (money you are owed by clients), you just no longer have to wait 30, 60 or even 90 plus days to get paid.
How do you factor an invoice?
- Speak to Contact Business Finance today
- We introduce you to the most suitable lender
- You enter an agreement with an invoice factoring company that suits your needs
- You then send invoices to the lender and receive payment straight away
Can a small business apply for Invoice Factoring?
Yes, although most lenders will require a minimum turnover. If you are a small business, it is very important to not waste time and speak to suitable lenders from the outset.
What types of Invoice Factoring are there?
There are various forms of invoice factoring. There are facilities that can allow a business to just factor a select few invoices and there are facilities that can enable a business to factor all their invoices and receive the maximum amount of funding available. There is an option to use a confidential facility, therefore your debtors do not have to know that you are using a factoring company. Facilities can be offered on a recourse and non-recourse basis and include credit protection, giving business owner’s piece of mind if their clients enter insolvency. It is very hard for a business owner to know what type of invoice finance facility is suitable for them. This is why it is great to speak to a broker that understands the market and can help tailor a facility.
What type of business uses Invoice Factoring?
Any business that raises an invoice to another business on credit terms can apply for an invoice factoring facility. Generally, we find that invoice factoring facilities are for growing businesses that require that extra working capital to assist with cash flow. Raising cash from your outstanding invoices is a great way to release money into the business which often means you can afford to take on more work. With invoice factoring you no longer have to wait to get paid by your clients and you can get a sudden cash injection to take more work on.
What is the difference between Factoring and Invoice Discounting?
Invoice Factoring – the lender conducts credit control, and the facility is fully disclosed. This means that your customers will see the lenders notice of assignment and bank details on the bottom of your invoice.
Invoice Discounting – credit control remains with your business and the facility is confidential, therefore your clients are not aware that you have a facility. The lenders notice of assignment does not appear on your invoices.
What is included in the credit control?
Credit control can be tailored to your business needs. It is important that clients realise that the majority of lenders will not physically chase all clients. It is quite often that lender will chase your 10 customers. However, if you require more assistance with credit control, speak to us today and we will put your business in contact with the most suitable lenders.
What is the difference between a Loan and Invoice Factoring?
A loan allows your business to receive a sum of money in one transaction. Your business agrees the length of the loan and makes regular capital & interest payments. If you do not make regular payments, you can default on a loan. Therefore, it is not ideal if your business becomes quiet and cannot service the loan as it is crucial you make regular payments.
Invoice factoring is a more secure method of borrowing as you are only lending money against sales invoices in which you were owed in the first place. The difference is that you do not have to wait 30, 60 or even 90 days for your clients to pay. Compared to a business loan, invoice factoring is better suited for regular cash flow, as it allows you to constantly inject working capital and feed money into the business. Unlike a loan, you cannot fall behind on your payments, as you are only borrowing against invoices that are due by clients. If your clients / debtors decide not to pay, there are insurances in place to make sure you and your business are protected.
Is Invoice Factoring a good idea for my business?
If you are a business that is constantly waiting to get paid and you think that you could take the company to the next level without this cash flow burden, then invoice finance sounds like it could be a great funding solution for you. At Contact Business Finance we will always be honest with you and weigh up your options at no cost.
Can I offer clients credit terms with Invoice Factoring?
Any form of invoice finance allows you to offer extended credit terms to clients. This is often a great weapon to have in your armoury if you are ever competing to win a contract. Your competitor might require payment upfront or after 30 days. However, if your business has an invoice finance facility you may feel more comfortable in offering your client much larger payment terms.
With invoice finance, lenders will quite often lend against invoices for 120 days or sometimes more depending on what industry you operate in. Please note, you should not just offer extended credit terms to anyone. Part of any invoice finance facility can also include the lender doing in depth credit searches on your clients, so you can see what terms / limits are suitable to offer.


